Direct Vs Regular Mutual Funds: What No One Tells You About The Cost Difference
Direct Vs Regular Mutual Funds: What No One Tells You About The Cost Difference
 By Marcus Ainsworth
·Editor-in-Chief ·
·
4 min read
Most investors in mutual funds don’t know they’re paying a commission. Not directly, not as a line item on a statement. It’s buried inside the expense ratio of their regular plan, deducted from the fund’s NAV daily, and never shows up as a separate charge anywhere they’d normally look.
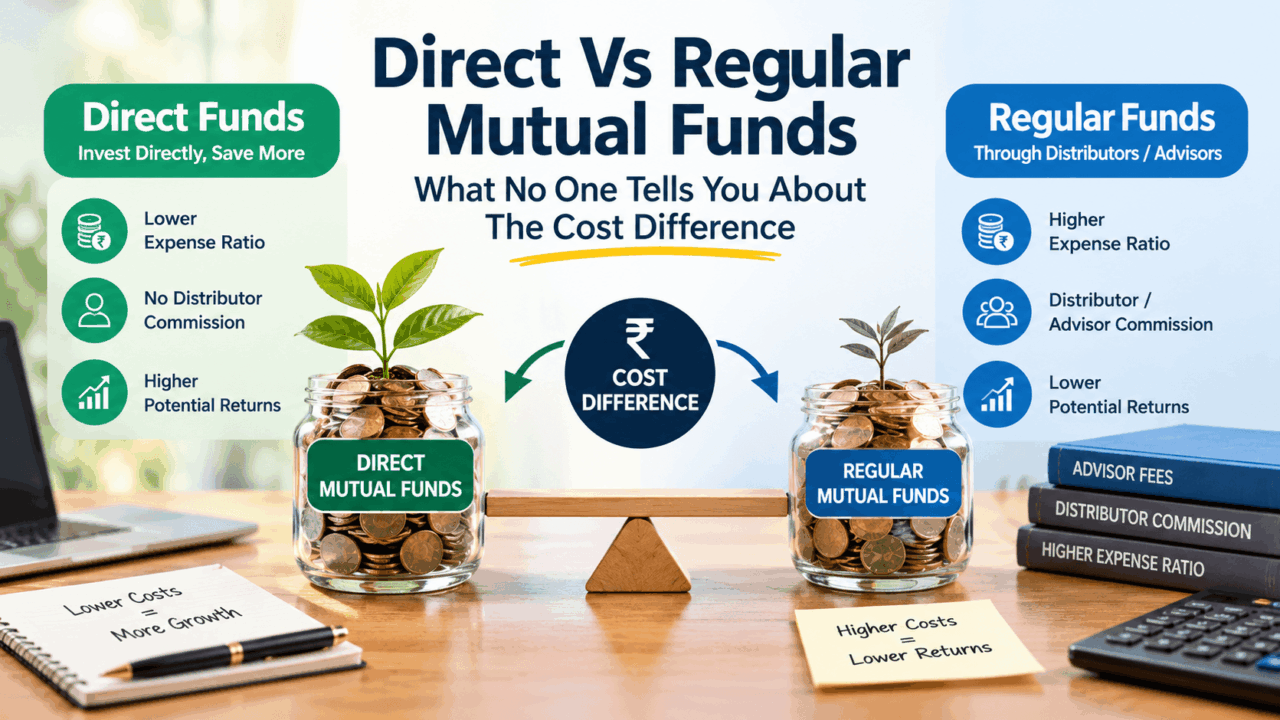
That invisibility is the problem. Because the difference between a direct plan and a regular plan isn’t about getting a different fund. It’s the same fund. Same portfolio. Same manager. Same strategy. The only difference is that one version includes a distributor’s commission baked into the annual cost, and the other doesn’t.
Sounds small. Over ten or fifteen years, it’s anything but.
What the Expense Ratio Actually Contains
Every mutual funds scheme charges an annual fee called the Total Expense Ratio. This covers the fund house’s management fee, operational costs, and in the case of regular plans, the commission paid to the distributor or platform that sold you the fund.
SEBI’s 2026 regulations made this clearer than before. The old single TER number is now unbundled into a Base Expense Ratio (the fund house’s management fee) plus separately disclosed brokerage and statutory levies. That transparency helps. But the core structural difference between direct and regular plans remains unchanged.
In a direct plan, there’s no distributor commission. So the expense ratio is lower. Typically somewhere between 0.5% and 1% lower annually, depending on the fund category and the fund house. In a regular plan, that commission is embedded in the cost you pay every single day you hold the fund.
You don’t see a bill. You don’t authorise a payment. The money just quietly leaves your corpus through a slightly lower NAV, every day, for as long as you’re invested.
Why the Gap Feels Small But Compounds Into Something Large
Here’s the part that doesn’t get enough honest airtime. A 0.5% to 1% annual cost difference sounds trivial. Half a percent? Who cares?
Compounding cares. Because that cost difference isn’t charged once. It’s charged every year, on a growing base. And over a long investment horizon, the cumulative drag is genuinely significant.
Think of it this way. Every year, a small slice of your corpus goes toward paying the distributor instead of compounding for you. That slice gets bigger as your corpus grows, because it’s a percentage, not a flat fee. Year one, the cost is modest. Year twelve, it’s working against a much larger base. By year fifteen or twenty, the gap between what you’d have in a direct plan versus a regular plan of the same mutual funds scheme isn’t a rounding error. It’s real money.
And you never lost it to the market. You lost it to a cost structure you may not have even known existed.
What You’re Actually Paying For in a Regular Plan
This is where the conversation gets uncomfortable. The distributor commission in a regular plan is meant to compensate the advisor or platform for their guidance. And for some investors, that guidance is genuinely valuable. If your distributor helps you choose the right fund, keeps you from panic-selling during corrections, and reviews your portfolio regularly, the commission might be earning its keep.
But here’s what nobody tells you. Many distributors don’t provide ongoing advice. They set up the SIP, earn trailing commission for as long as you stay invested, and never speak to you again unless you call them. You’re paying an annual fee for a service that was delivered once.
That’s not a criticism of all distributors. Some are excellent. But the mutual funds industry’s commission structure pays them the same regardless of whether they provide ongoing value or vanish after the initial sale. The cost to you doesn’t change either way.
The Direct Plan Trade-Off Nobody Mentions
Going direct isn’t free of trade-offs. You lose the distributor’s hand-holding. Nobody calls you during a market crash to talk you off the ledge. Nobody nudges you to increase your SIP after a salary hike. Nobody restructures your portfolio when your goals change.
If you’re disciplined, financially literate, and comfortable making these decisions yourself, direct plans are the obvious choice. The lower cost compounds in your favour for decades.
If you’re not, and you genuinely need behavioural coaching and periodic portfolio reviews, a fee-only registered investment advisor might be a better option than either route. They charge a flat or percentage-based advisory fee, recommend direct mutual funds plans, and you avoid the embedded commission entirely. The total cost is transparent and the advice isn’t conflicted by commission incentives.
Conclusion
The cost difference between direct and regular mutual funds plans isn’t dramatic in any single year. That’s why most investors ignore it. But compounding doesn’t care about any single year. It cares about every year, stacked on top of each other, for as long as you’re invested. Before choosing a plan, understand exactly what you’re paying, who you’re paying it to, and whether that cost is earning its place in your portfolio. If it isn’t, every year you stay in a regular plan is a year the gap widens.